What the “One Big Beautiful Bill Act” Means for 2026 Charitable Giving
...and why the ImpactAssets Donor Advised Fund can help before year end.
With 2026 coming to a close, donors still have time to review their giving under the One Big Beautiful Bill Act’s (OBBBA) new charitable rules.
Key Takeaways
- New rules apply to 2026 gifts. Donors should be aware of OBBBA’s new AGI floor (0.5% for itemizers) and the 35% deduction cap.
- “Bunching” may be beneficial. Aggregating multiple years of giving into one 2026 gift helps clear the new AGI floor more efficiently than annual gifts. DAFs make bunching simple because you can give in one year and recommend grants for years to come.
- A DAF separates the tax decision from the giving decision. If you contribute now, you lock in this year's deduction while you decide which nonprofits and impact investments to pursue.
- Appreciated assets can do more than cash. Donating stock, business interests, and other noncash assets that have been held for more than a year may reduce capital gains tax, stacking additional savings on top of the deduction, especially valuable in a high-income year (IPO, sale, bonus, etc.).
What Changed for Charitable Giving in 2026?
Beginning January 1, 2026, OBBBA introduced several adjustments to how charitable contributions are treated for tax purposes. These changes are already in effect for gifts made in 2026, so they directly affect any giving you do before year-end.
- For itemizers: Deductions apply only to gifts that exceed 0.5% of adjusted gross income (AGI). This creates a new “floor” before charitable deductions begin. A new deduction for people who don't itemize (up to $1,000, or $2,000 for joint filers) doesn't apply to gifts to a DAF.
- For high-income taxpayers: Donors in the 37% bracket save no more than 35 cents in federal tax for each deducted dollar.
Given these changes, high earners may benefit from revisiting their charitable giving strategy for 2026.
How Does a Donor Advised Fund Help Under the New Rules?
A donor advised fund (DAF) lets you separate the giving decision from the tax decision. You can donate now, take this year’s deduction, and recommend grants to nonprofits later. Contributions are irrevocable. OBBBA’s new rules make that separation more valuable than ever. Because the new floor applies every year, putting several years of giving into one year means paying it once.
- Consider donating appreciated assets. Beyond publicly traded stock, an ImpactAssets DAF can accept concentrated stock positions, private business interests, and real estate. That lets you give from the part of your wealth that may have grown the most.
- Bunch multiple years into one gift. Put several years’ worth of giving into your DAF in 2026, then recommend grants on the schedule you would have followed anyway. The nonprofits you support can continue without a gap.
- Invest donated assets for positive impact. You can invest contributions to an ImpactAssets Donor Advised Fund in funds and companies that align with your values. Invest in sectors such as renewable energy, sustainable agriculture, affordable housing, and health equity, all while you take the time to plan your long-term giving strategy.
What this Looks Like in Practice*
CASH CONTRIBUTIONS
A donor with $1M AGI who gives $100,000 a year hits the 0.5% floor annually, forfeiting a small deduction each time. Contributing three years at once ($300,000) hits the floor only once. That preserves roughly $10,000 more in deductible giving.
This assumes $1M of AGI each year, that the donor itemizes, and that no other limits apply. The extra $10,000 is deductible giving, worth up to about $3,500 in federal tax at 35 cents per dollar.
That same $300,000 gift is even more effective when you fund it with appreciated stock rather than cash. If you donate shares held more than a year, you never pay capital gains tax on the growth. By contrast, you would owe that tax if you sold the shares first. Gifts of appreciated stock are deductible up to 30% of AGI a year (cash up to 60%), with five years to use any excess.
APPRECIATED ASSETS
The ability to donate appreciated assets is especially relevant for donors with long-held, highly appreciated stocks, or individuals whose company went public recently. These people may have a highly concentrated position in their portfolio that they want to reduce while limiting taxes.
Consider a founder whose company recently went public. Her 2026 AGI is $15M, and her position has a very low cost basis. She donates $4M of shares with a $200,000 basis to her DAF:
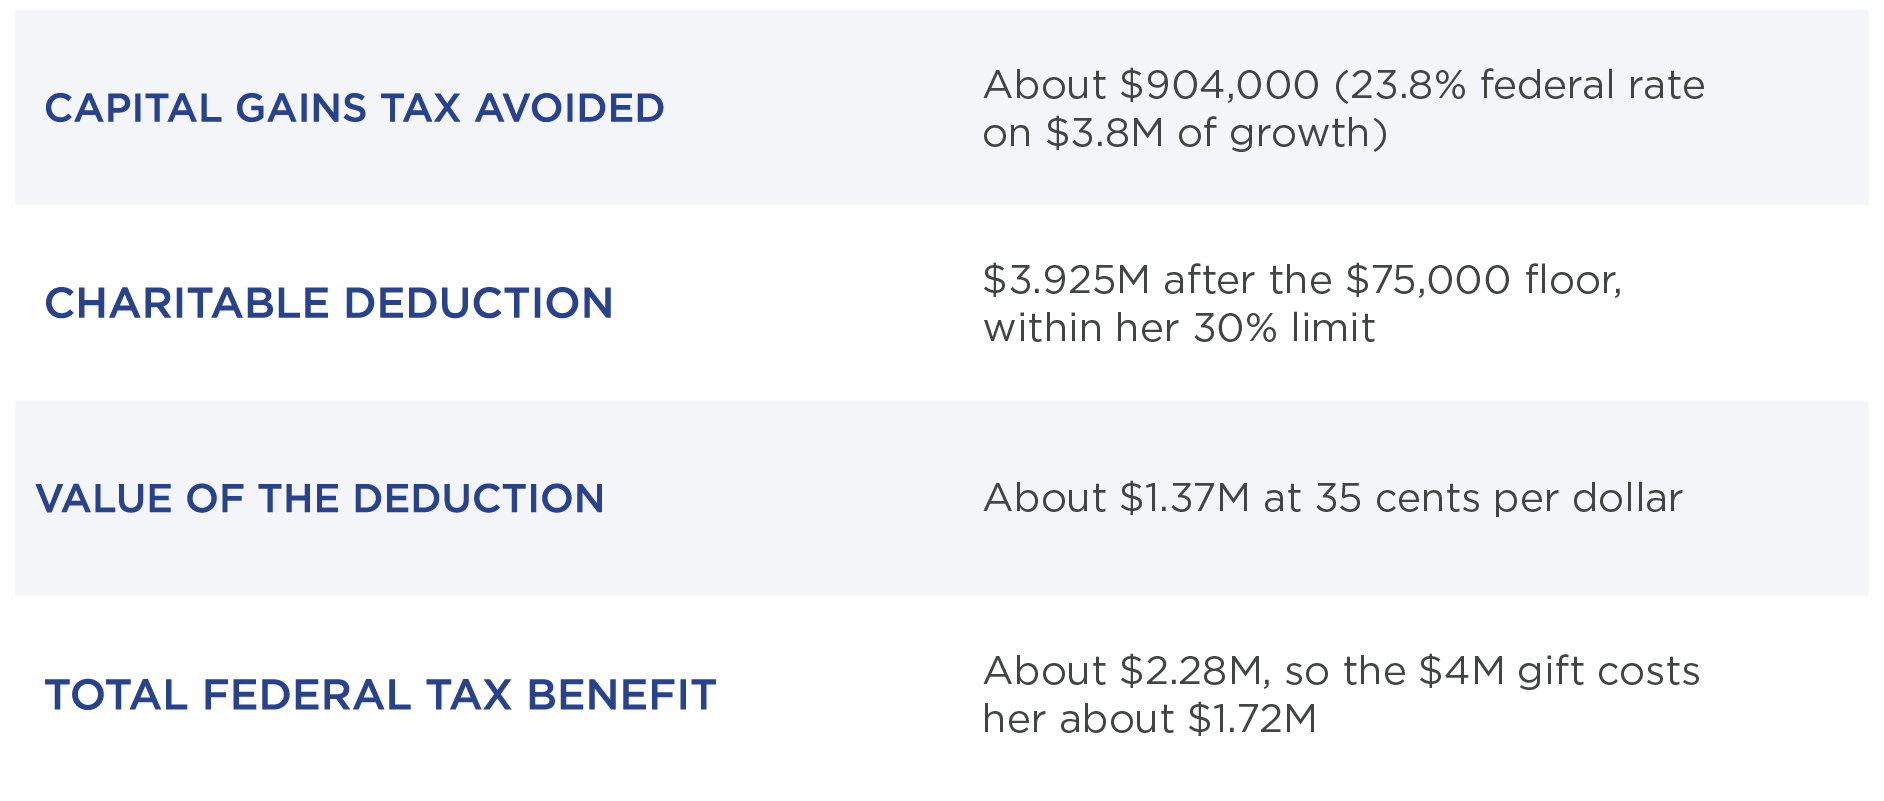
Had she sold the shares first and donated the after-tax proceeds, her DAF would have received about $3.1M instead of $4M. Donating restricted or privately held assets takes legal, valuation, and transfer review, and ImpactAssets has the expertise to handle it. Accepted assets (subject to review and acceptance) include (but are not limited to):
- Public stock
- Private company stock
- Restricted securities
- Cryptocurrency
- Fine art and collectibles
- Real estate
Because complex and restricted assets take time to transfer, we recommend engaging with us early to ensure your gift is completed in 2026.
*These case studies are entirely hypothetical and provided for illustrative purposes only. The scenarios do not include state and local taxes in their calculations. They do not depict any actual donor. Consult your tax advisor on strategies that make sense for your unique situation.
Why Year-End Timing Matters
The new AGI floor and the cap on high-bracket deductions apply to the calendar year in which a gift is made. That means decisions made before December 31 determine what counts toward this year’s deduction.
High-income years can be the best years to give, depending on your income, the assets you hold, and your goals. Donors with a liquidity event, IPO, business sale, carried interest payout, or large bonus in 2026 have the most to gain from giving before year-end. Large gifts concentrated in high-income years can be especially tax-efficient under the new rules depending on your situation .
To count for 2026, the gift has to be complete by December 31, meaning the assets are in your DAF, not just requested. Public stock can move in days. Private stock, restricted shares, and real estate can take weeks, so start early.
What Should You Do Before December 31?
The December 31 deadline will be here soon. Talk to your advisor and review your giving strategy in light of OBBBA’s new rules, especially if you're experiencing an extraordinary income year.
Frequently Asked Questions
How does the 0.5% floor work?
If you itemize, only what you give above 0.5% of your AGI counts toward your charitable deduction. With $1M of AGI, the first $5,000 you give isn't deductible.
Can giving below the floor carry forward?
Giving below the floor carries forward only in limited cases, generally when your gifts also exceed the annual AGI limits. Ask your tax advisor.
Does the 35% cap reduce how much I can deduct?
The cap works by reducing itemized deductions. For donors in the 37% bracket, each deducted dollar saves about 35 cents instead of 37.
What are the limits for donating appreciated assets?
Generally, you can deduct gifts of appreciated stock held more than a year up to 30% of your AGI each year. For cash, the limit is 60% of AGI. If you give more than the limit, you have five years to use the excess.
When does a gift have to be complete to count for 2026?
To count for 2026, a gift has to be complete by December 31, with the assets in your DAF. Complex assets take longer, so start early.
LEGAL AND PROGRAM DISCLAIMER: This is not a solicitation to buy or sell securities, nor a private placement offering pursuant to any private placement memorandum that must be issued to qualified investors. It is an informational description of charitably oriented, social purpose investment options that have been approved by ImpactAssets only for use in its donor advised fund asset base. It is only for use by its donors. This does not constitute tax advice. Please note there are a number of factors to consider when assessing the tax implication of gifts to charity. Individuals should consult with a tax specialist before making any charitable donations.
ImpactAssets Capital Partners PB LLC (“IA Capital”) is an investment adviser registered with the SEC. The content of this website is not a solicitation or offer to sell investment advisory services, nor is it a solicitation or offer to sell securities. All content of this website is for informational purposes only and should not be relied upon as investment advice. Information is subject to change at any time, and IA Capital is under no obligation to provide updates or amendments. Investment in securities involves the risk of loss. Past performance is no guarantee of future returns.